Daewon Media (048910) Stock Forecast: What the Chiikawa Movie Is Worth, a KRW 9,570 Fair Value and When to Sell
Daewon Media (048910) stock forecast, worked out through the Chiikawa movie. “Chiikawa the Movie: The Secret of Mermaid Island” drew 11.78 million viewers in Japan, and in Korea it is imported by Daewon Media and distributed by CJ ENM. This post estimates how many Koreans will see it, how much of the box office reaches Daewon Media, what Chiikawa merchandise adds, and then a fair value and a selling window. Data as of October 8, 2026.
- Daewon Media is the importer of the Chiikawa movie; CJ ENM distributes it. Korea: 818,000 admissions in 8 days. Japan: 11.78 million in 75 days.
- Author’s base case: 1.69 million final Korean admissions (bear 1.47 million, bull 2.21 million); Daewon’s share of the KRW 17.7bn box office is KRW 7.03bn.
- Film operating profit KRW 1.7bn + merchandise KRW 590mn = KRW 2.29bn, or KRW 139 a share (1.7% of the share price), calibrated on Daewon’s own results from The Boy and the Heron and The First Slam Dunk.
- Author’s fair value KRW 9,570 (2027E EPS KRW 857 × 11 + KRW 139), 16.0% above today. 10 percentage points of distribution growth moves it KRW 960; 1 million more viewers moves it KRW 80.
- Since July 22: retail investors sold KRW 900mn, private equity funds bought KRW 475mn and foreign investors KRW 269mn. The funds have not sold on a single day.
- Switch 2 peaked 16 trading days after launch and The Boy and the Heron 61 trading days after release. First selling window: late October to mid-November (1.5 million admissions plus Q3 results).
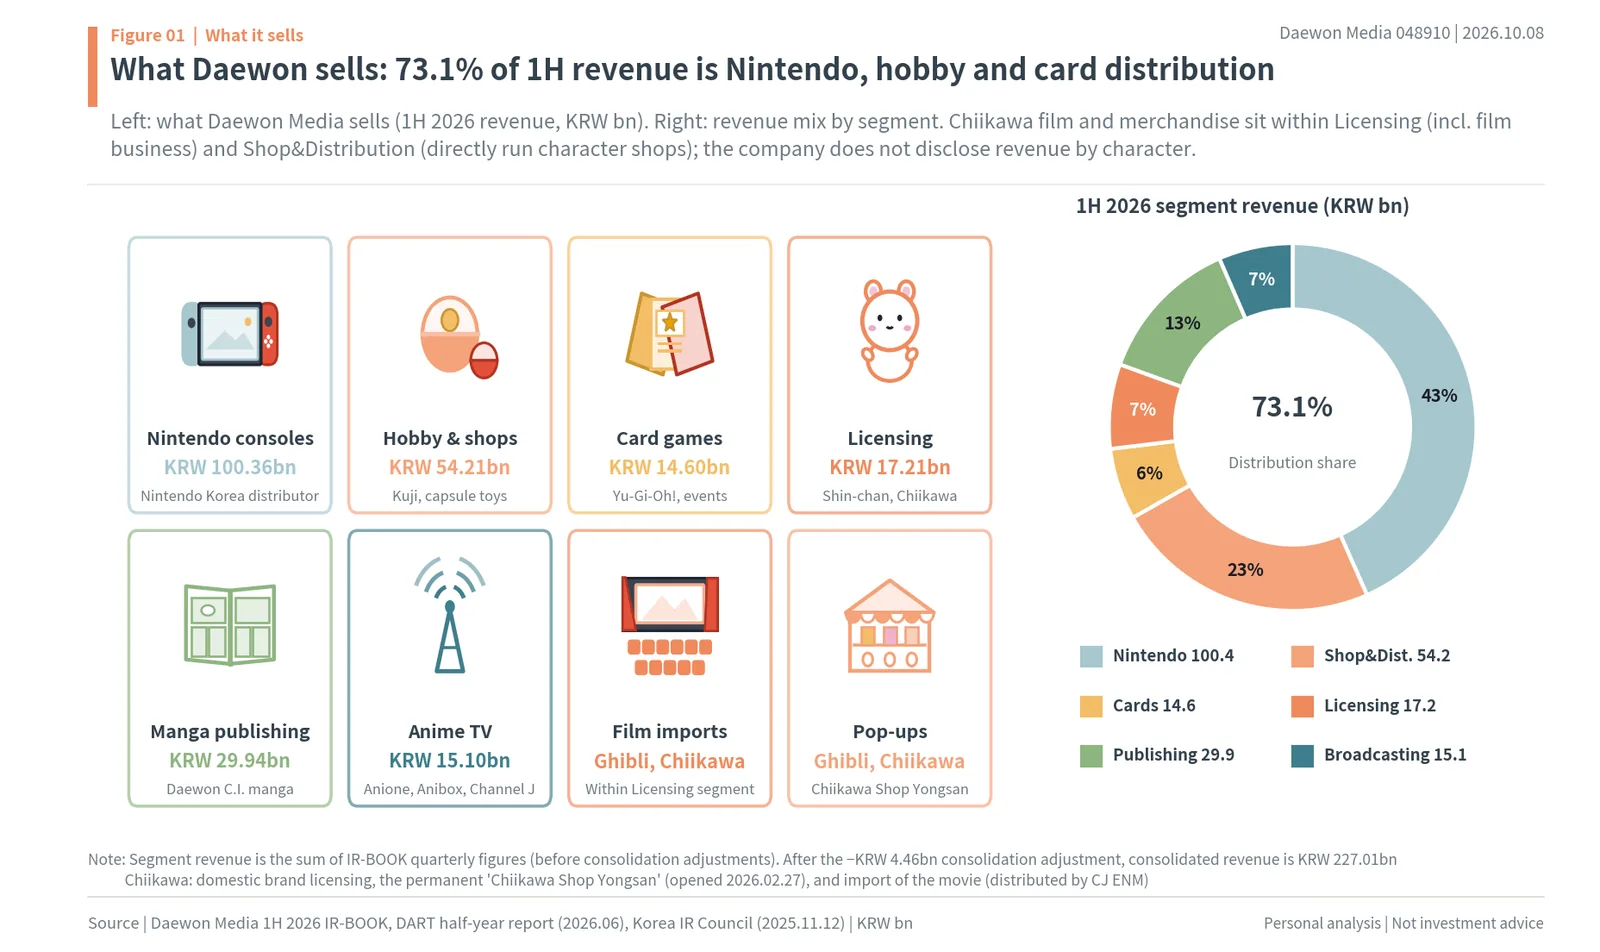
Key takeaways
- In the author’s base case, the Chiikawa movie (imported by Daewon Media, distributed by CJ ENM) reaches final admissions of 1.69 million, and the operating profit left to Daewon, KRW 2.3bn (KRW 1.7bn from the film + KRW 600mn from goods), is worth KRW 139 a share.
- The author estimates operating profit of KRW 20.78bn in 2026 → KRW 19.31bn in 2027 and a fair value of KRW 9,570 (2027 EPS of KRW 857 × 11 + KRW 139), 16.0% above today’s price.
- As with the Switch 2 and the Ghibli film, this stock peaked on the day the story was hottest: the first selling window is late October to mid-November, when 1.5 million admissions and Q3 results overlap.
As of: October 8, 2026
Ticker: Daewon Media (048910, KOSDAQ)
Reference close: KRW 8,250 (KRX close, October 8, 2026)
This is the author’s personal analysis and opinion.
The author’s calculations and estimates are not confirmed facts.
1. This report works out what the Chiikawa movie is worth to Daewon Media, a fair value for the stock and a selling window, based on the author’s estimates.
2. It asks five questions: what the stock is worth, how much Chiikawa (known in Korea as Meonjakgwi) goods add, how the films Daewon imported before performed, whether a sell-the-news drop is coming, and when to sell.
3. One correction first: Daewon Media is the film’s importer, and CJ ENM is the distributor that puts it in theaters (KOBIS, the Korean Film Council’s box-office system).
4. The order is: what Daewon sells → the film from Japan → how many people will see it → Daewon’s share → goods → share price and trading flows → sell-the-news → fair value → when to sell.
5. The conclusion first: lines for Chiikawa, profit from Nintendo; Chiikawa is worth KRW 139 a share, and the distribution business sets the rest of the KRW 9,570 fair value.
1. What Daewon Media Sells: Nintendo Korea Distribution Is 73.1% of Revenue
6. Daewon Media started in 1977 as an animation producer and is now a company that imports foreign characters and sells them in many forms.
7. It imported and distributed Studio Ghibli films in the 1990s and 2000s, and it is the official Korean distributor of Nintendo consoles (IR-BOOK).
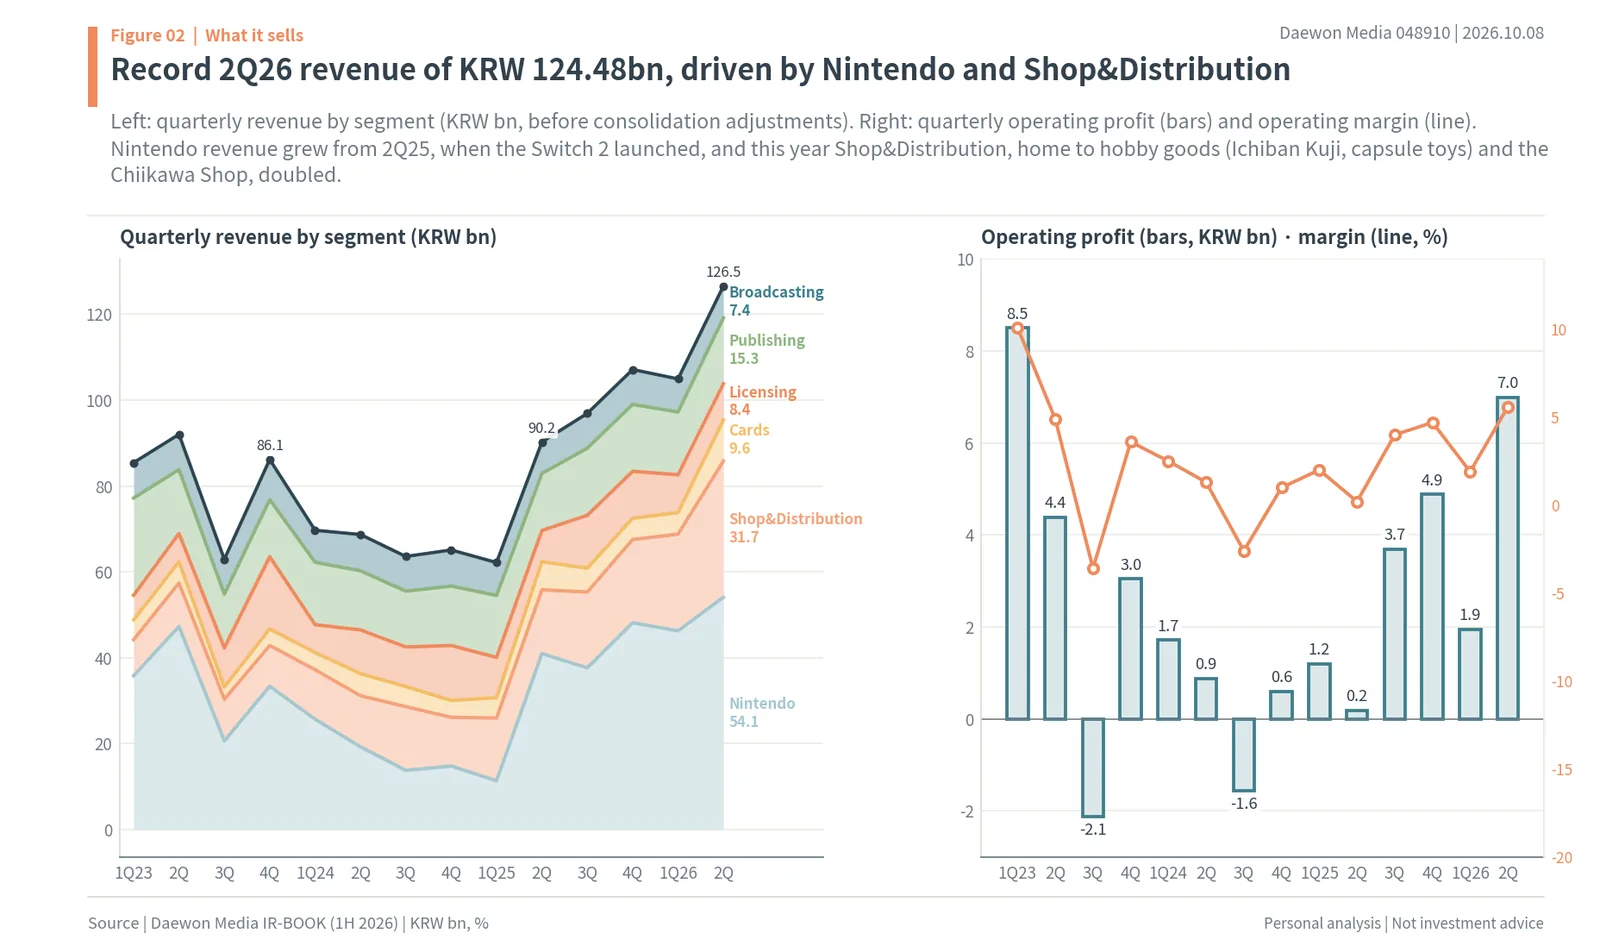
8. Of first-half revenue of KRW 227.0bn this year, 73.1% came from Nintendo, hobby and card distribution.
9. By size, Nintendo brought in KRW 100.36bn, Shop & Distribution (Ichiban Kuji prize lotteries, capsule toys and character shops) KRW 54.21bn, and cards KRW 14.60bn.
10. Through the end of June this year, Daewon Media had sold a cumulative 2.05 million Nintendo Switch consoles and 7.3 million games, including 138,618 consoles in the first half of this year alone.
11. The Korea IR Service wrote that, as Nintendo Korea’s official distributor, Daewon handles about 60% of console distribution in Korea.
12. Licensing brought in KRW 17.21bn and covers royalties from characters such as Crayon Shin-chan, Chiikawa and SpongeBob, plus the film business.
13. The company does not disclose revenue by character, so Chiikawa’s share has to be calculated separately.
14. Q2 revenue of KRW 124.48bn was a record, and operating profit was KRW 6.99bn (5.6% margin).
15. Most of the revenue growth came from Nintendo and Shop & Distribution: Nintendo grew from Q2 2025, when the Switch 2 launched, and this year Shop & Distribution doubled from a year earlier.
16. First-half operating profit in the distribution segment was KRW 8.2bn (4.8% margin), up sharply from KRW 1.5bn a year earlier (Bloter).
17. So of consolidated operating profit of KRW 8.94bn, content, broadcasting and publishing contributed only a little over KRW 700mn.
18. Daewon Media’s profit now comes from Nintendo and hobby distribution, and Chiikawa is an add-on on top of that.
2. Chiikawa the Movie: 11.78 Million in Japan, 818,000 in Korea in 8 Days
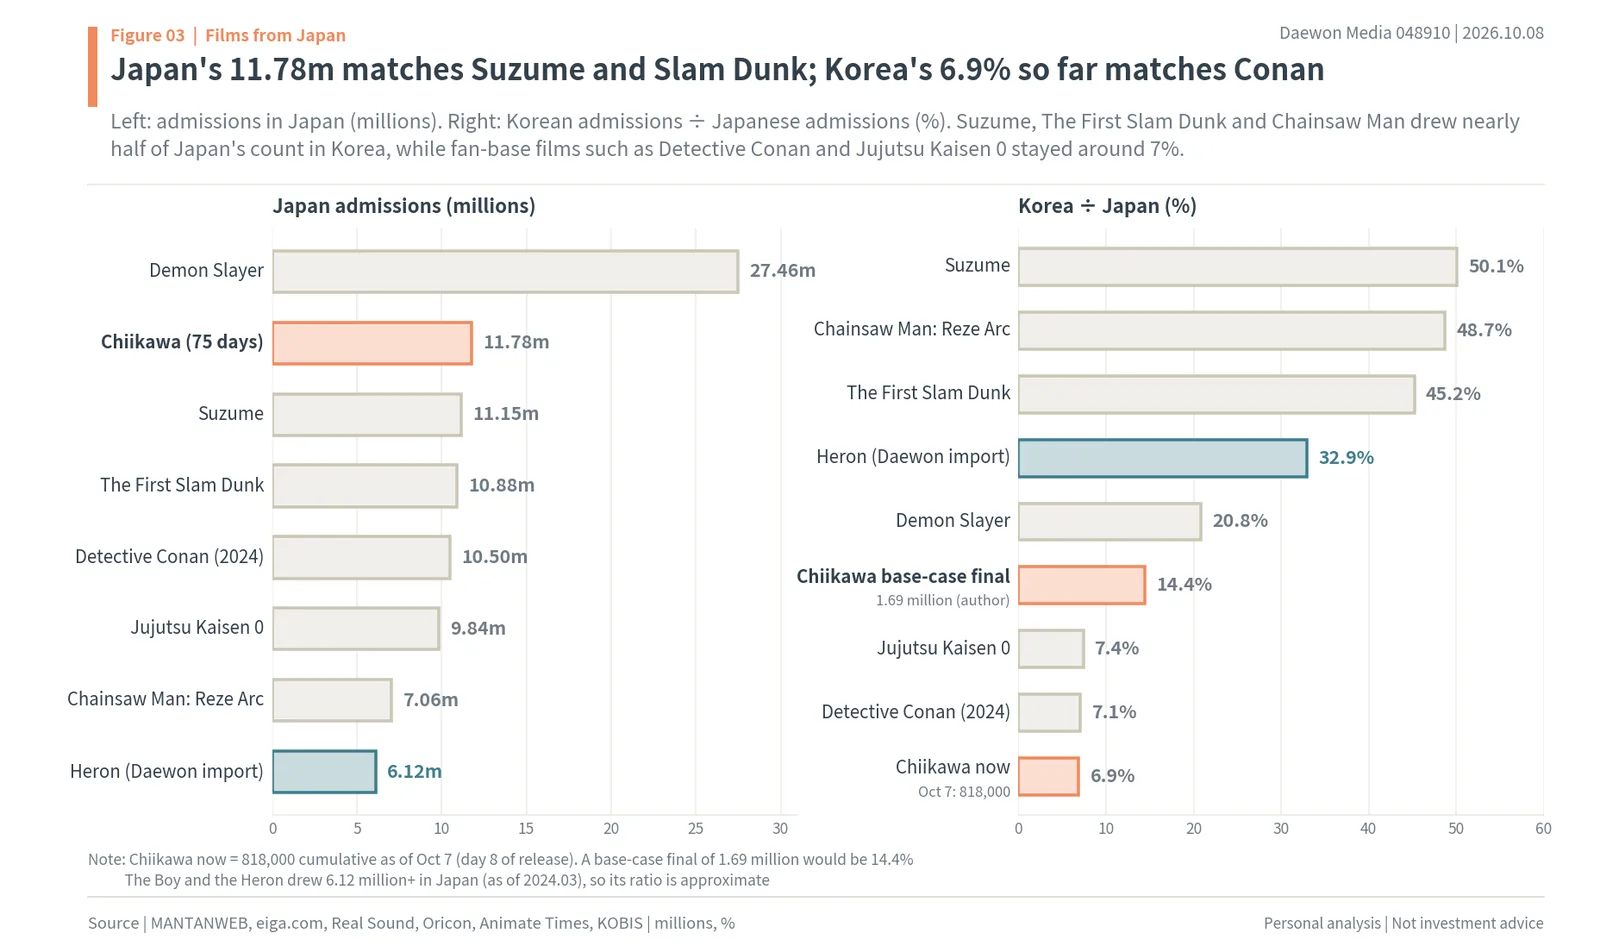
19. Chiikawa the Movie: The Secret of Mermaid Island opened in Japan on July 24 and drew 11.78 million admissions and JPY 17.2bn in 75 days.
20. It is the No. 1 release in Japan this year, and its admissions are similar to Suzume (11.15 million) and The First Slam Dunk (10.88 million).
21. But the ratio of Korean to Japanese admissions varies widely from film to film.
22. Suzume, The First Slam Dunk and Chainsaw Man – The Movie: Reze Arc drew close to half of their Japanese admissions in Korea, and Demon Slayer: Infinity Castle drew 20.8%.
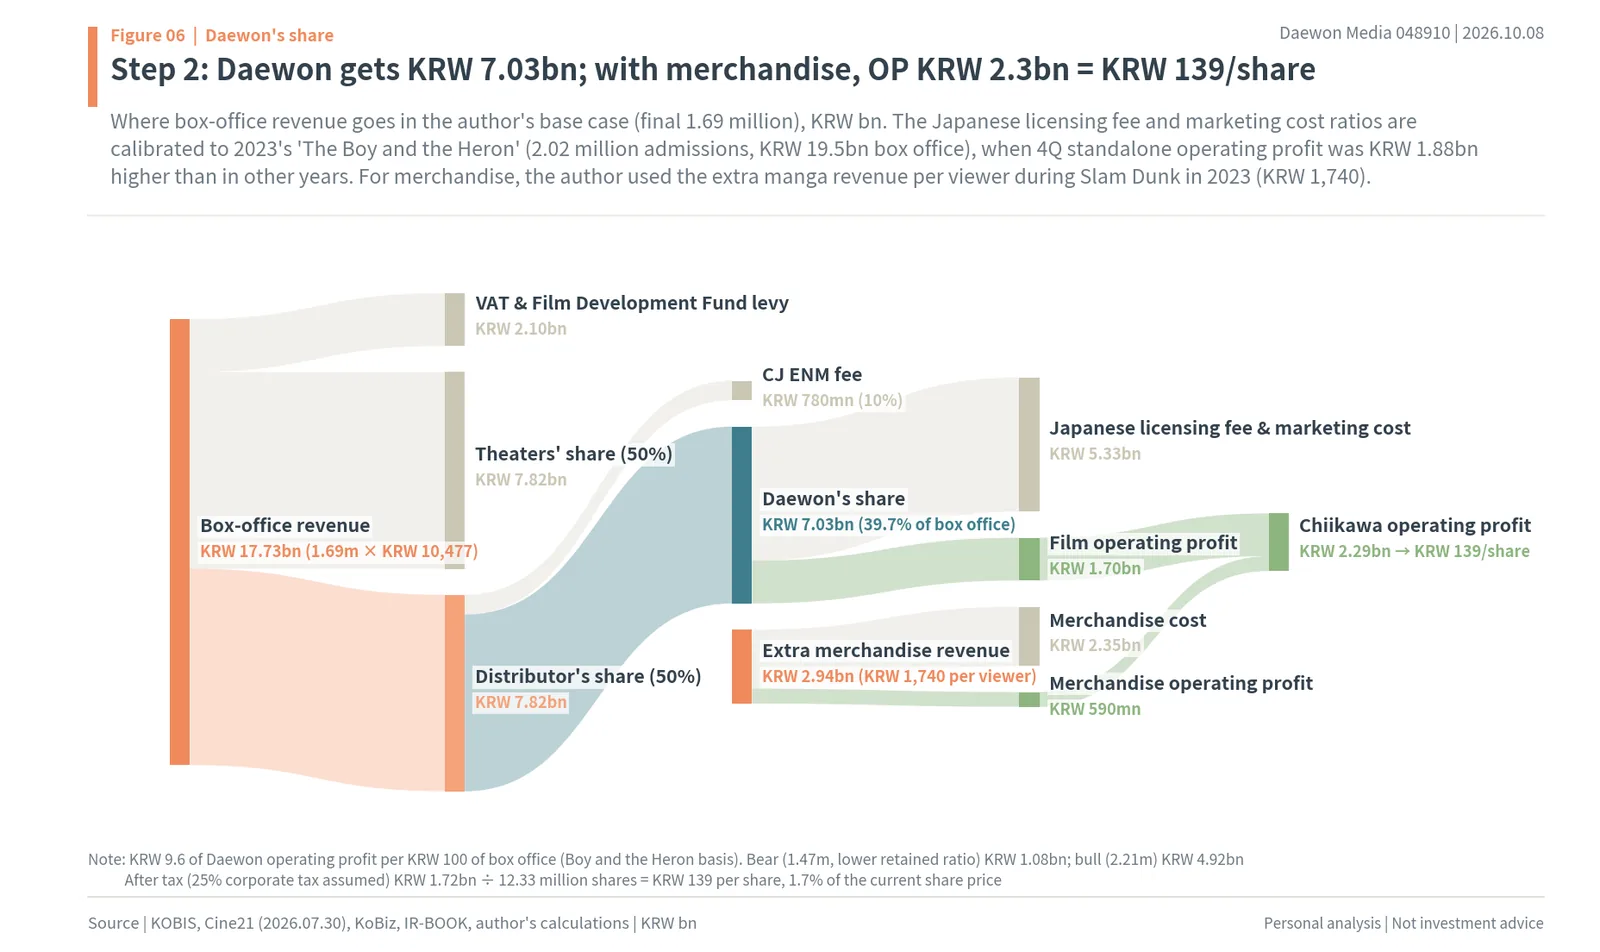
23. Films with a fixed fan base, such as Detective Conan and Jujutsu Kaisen 0, were in the 7% range.
24. Eight days after release, Chiikawa is at 6.9% of its Japanese total, close to the start of a fan-base film.
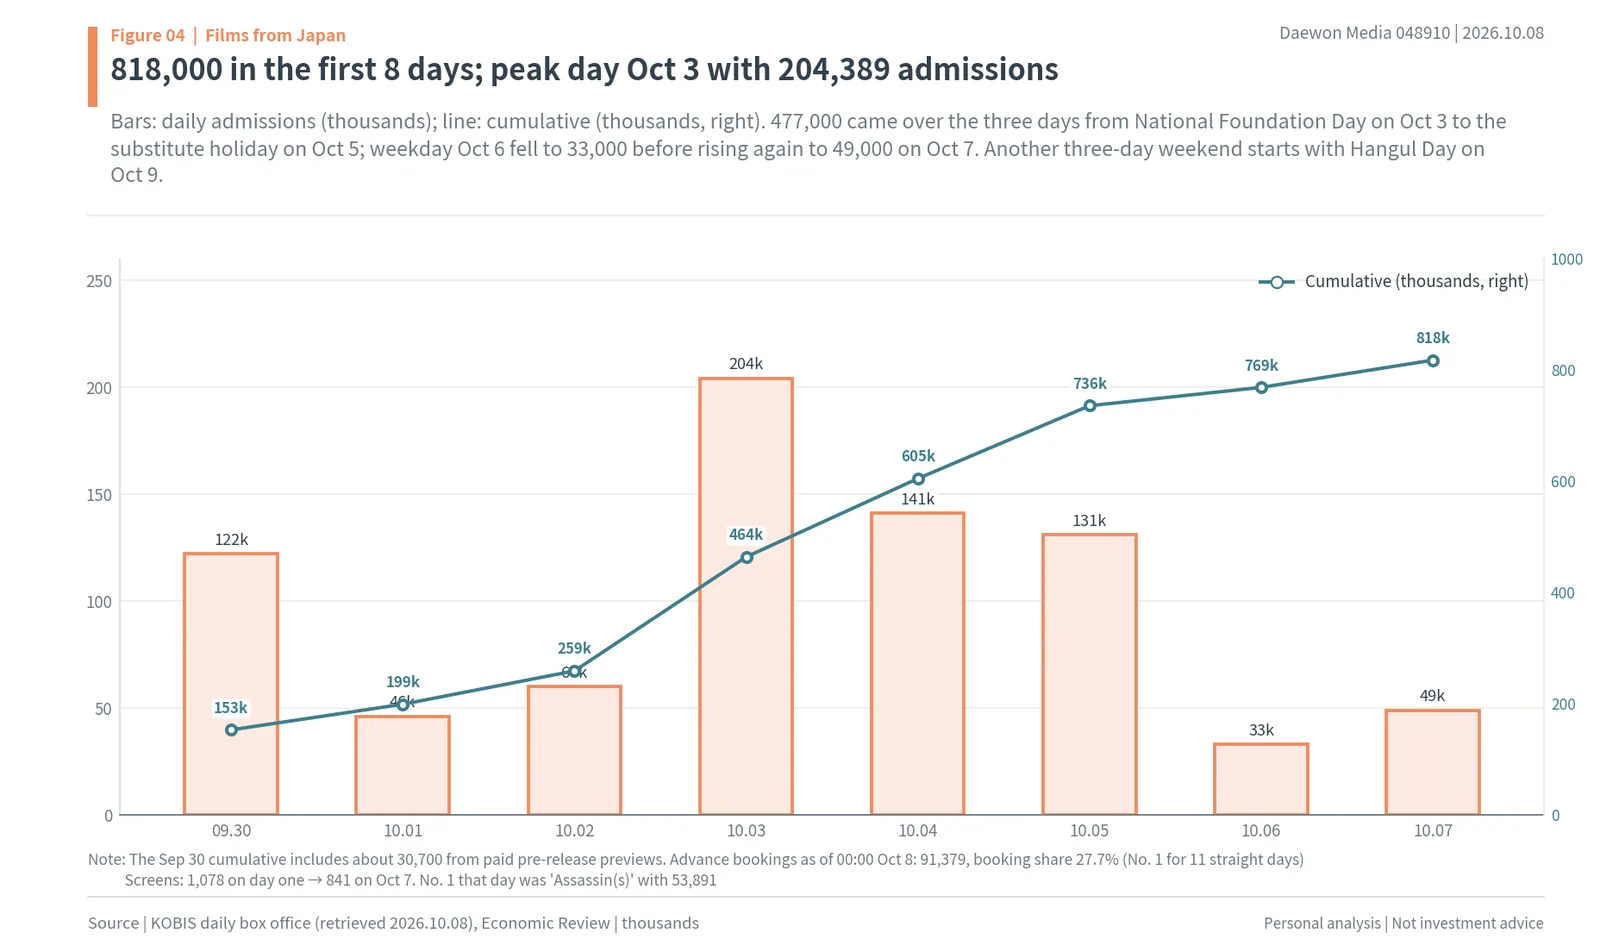
25. On its first day in Korea it drew 122,291 admissions on 1,078 screens (KOBIS).
26. Over the three days from October 3 (National Foundation Day) to October 5 (a substitute holiday), 476,816 people came, and the busiest day was October 3 with 204,389.
27. Admissions fell to 33,089 on October 6, a weekday, then rose again to 49,227 on October 7, less than 5,000 behind that day’s No. 1 film, Assassin(s).
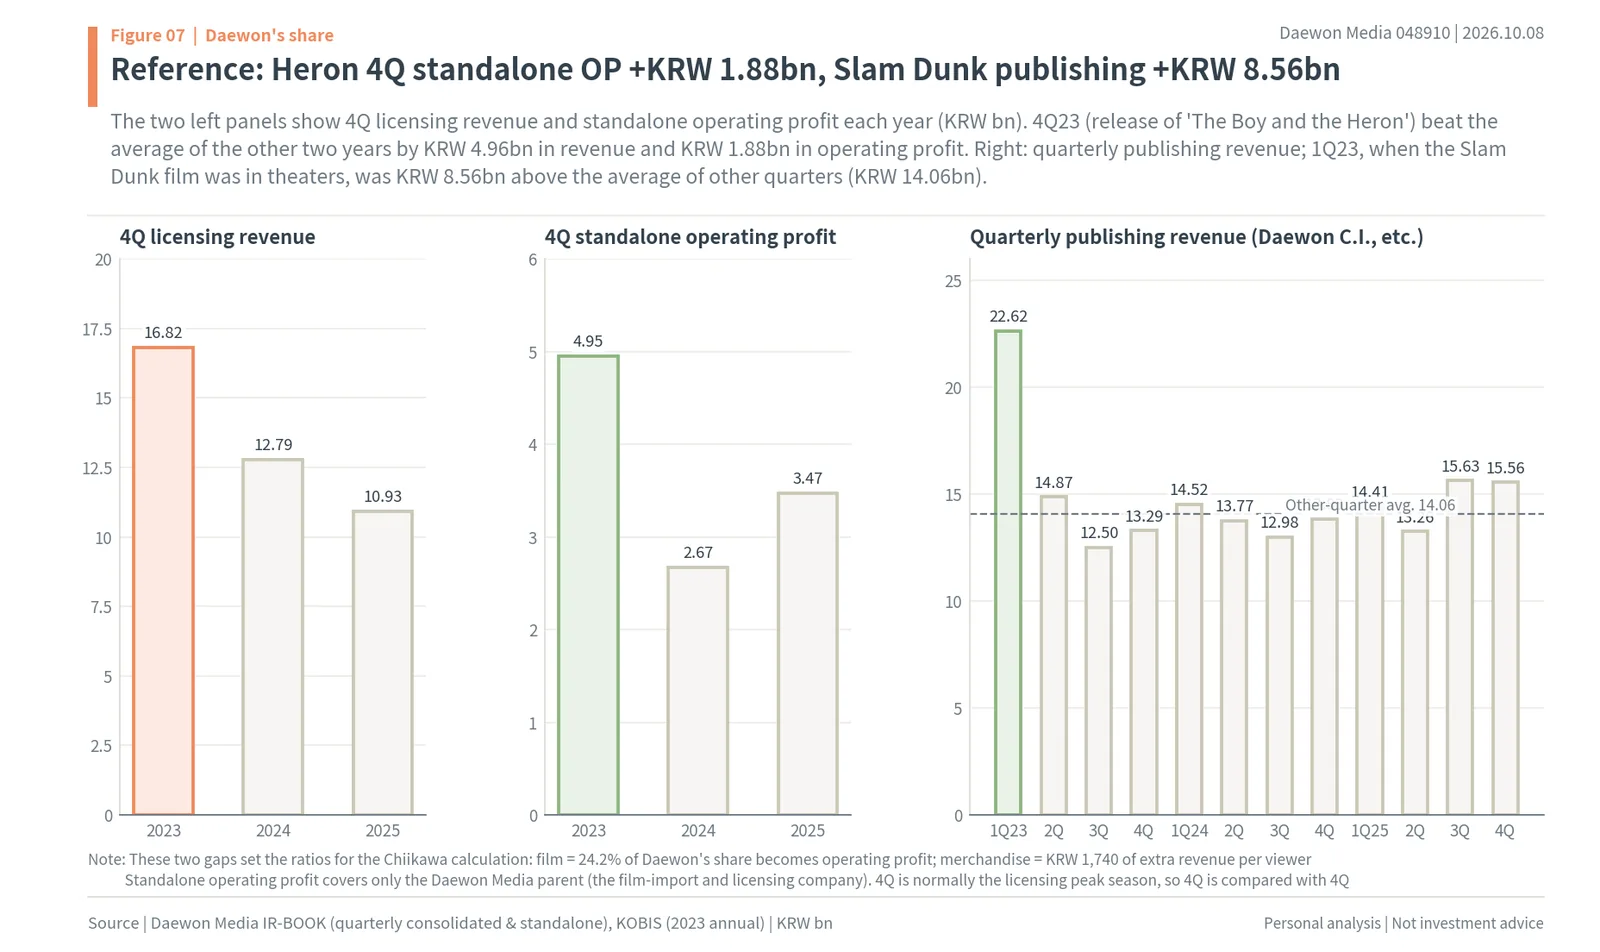
28. Through October 7, cumulative admissions were 818,000 and cumulative box office was KRW 8.57bn, so each viewer paid KRW 10,477 on average.
29. As of midnight on October 8, advance bookings were 91,379 with a 27.7% booking share, making it No. 1 in advance bookings for 11 days in a row.
30. Cumulative admissions are 818,000 after eight days, and another three-day holiday starts on October 9 (Hangeul Day), so the author expects the film to pass 1 million during this holiday.
3. Chiikawa Movie Korea Box Office Forecast: 1.69 Million Base Case
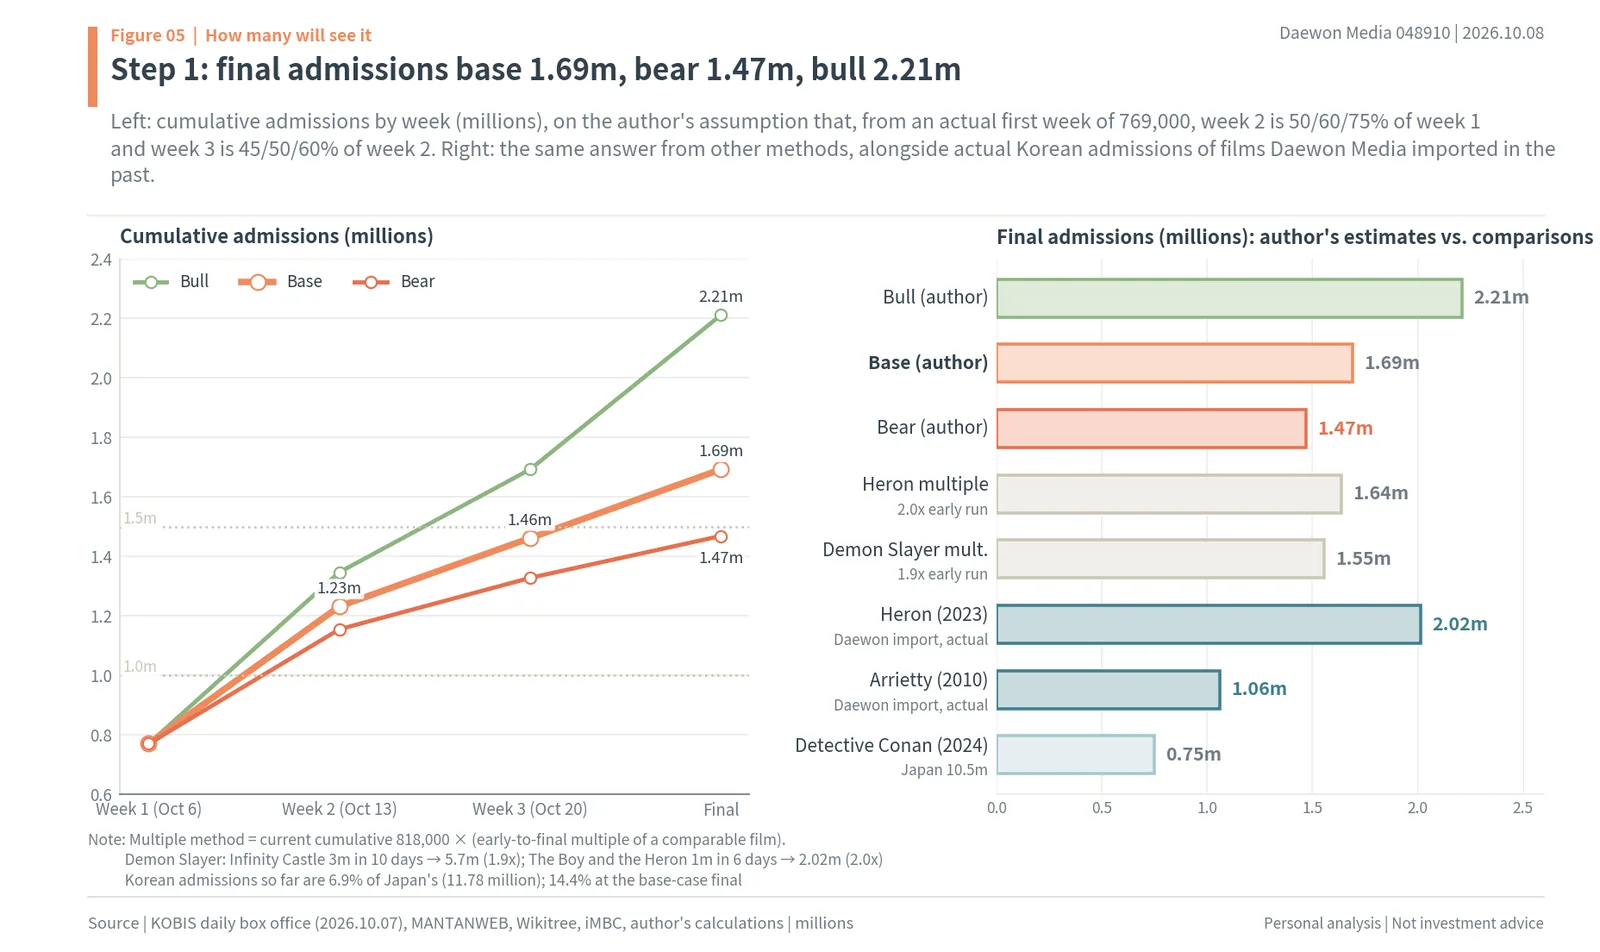
31. Final admissions were estimated from how much they fall each week: the first week (September 30 to October 6), including paid previews, drew 769,121.
32. In the base case, week two is 60% of week one, week three is 50% of week two, and each later week is 50% of the one before (author’s assumption).
33. That gives 1.23 million by the end of week two (October 13), 1.46 million by the end of week three (October 20), and a final 1.69 million.
34. The bear case (50%, 45%) gives 1.47 million and the bull case (75%, 60%) 2.21 million.
35. As a cross-check, multiplying the current total by comparison films’ ratio of final to early cumulative admissions gives 1.64 million based on The Boy and the Heron and 1.55 million based on Demon Slayer.
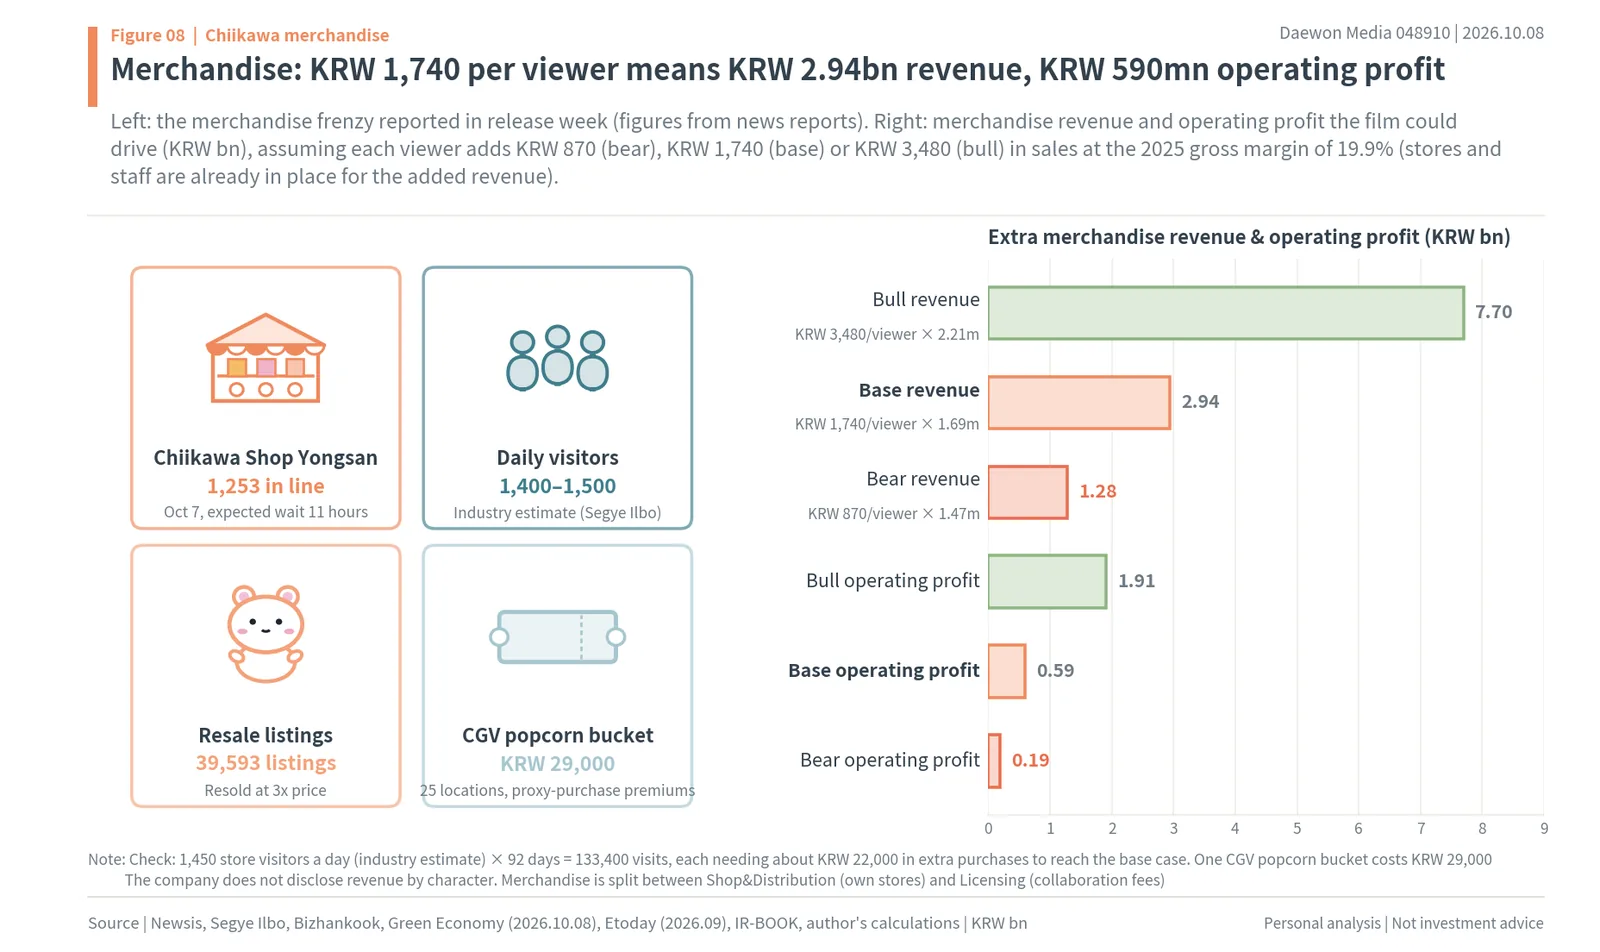
36. Actual Korean admissions for films Daewon Media imported were 2.02 million for The Boy and the Heron and 1.06 million for Arrietty.
37. The base case of 1.69 million is 14.4% of Japan’s total, more than double Detective Conan (750,000) and less than The Boy and the Heron.
38. Step 1 concludes with final admissions of 1.69 million (bear 1.47 million, bull 2.21 million) and base-case box office of KRW 17.7bn.
4. Daewon Media’s Share: KRW 7.03bn of a KRW 17.7bn Box Office
39. Taking 10% VAT and the 3% film development fund out of box office leaves net ticket revenue, which theaters and the distributor split in half (Cine21).
40. From the distributor’s share, CJ ENM takes a 10% fee and sends the rest to Daewon as the importer (KOBIZ import guide).
41. So Daewon’s share is 39.7% of box office, which at the base case of 1.69 million is KRW 7.03bn of KRW 17.7bn.
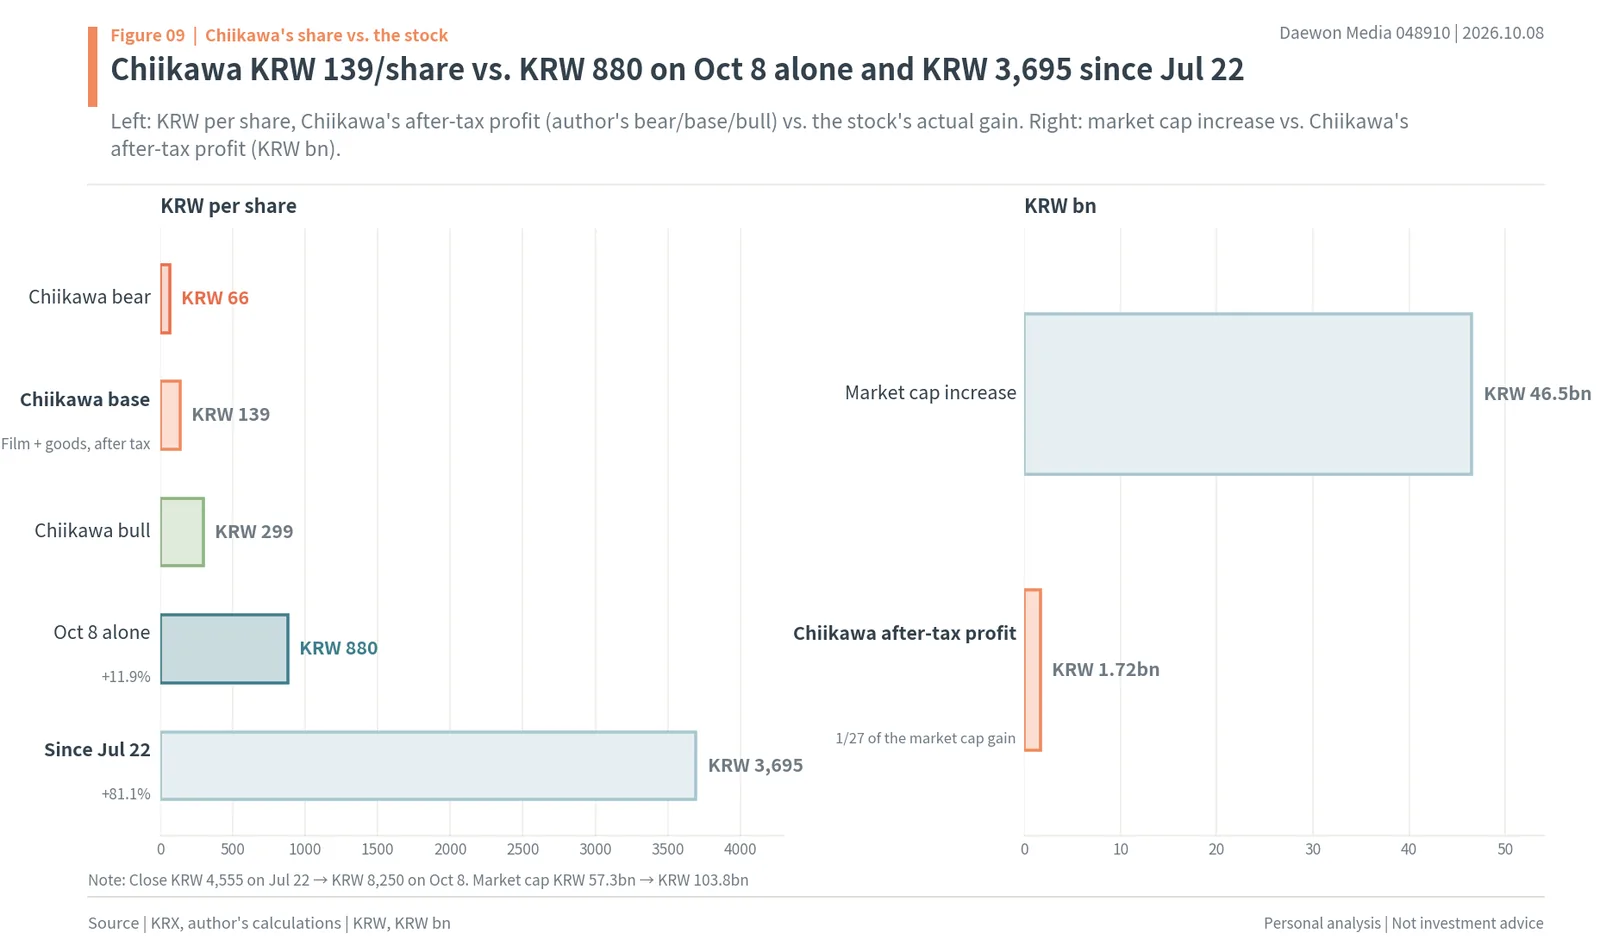
42. Out of this money Daewon pays the Japanese rights fee (a minimum guarantee plus a box-office share) and marketing costs, and the amounts have not been disclosed.
43. So the ratio was calibrated with The Boy and the Heron, which the same company imported in 2023.
44. The result first: Chiikawa operating profit including goods (Section 5) is KRW 2.3bn, or KRW 139 a share after tax.
45. That film drew 2,009,398 admissions and KRW 19.5bn in box office in Korea in 2023 (KOBIS 2023 annual).
46. In Q4 2023, when it opened, licensing revenue was KRW 16.82bn, KRW 4.96bn more than the average of Q4 2024 and Q4 2025.
47. In the same quarter, Daewon Media’s standalone (parent-only) operating profit was KRW 4.95bn, KRW 1.88bn more than the average of the other two years’ Q4.
48. If this KRW 1.88bn is taken as the film’s profit, 24.2% of Daewon’s share (KRW 7.75bn) was left after rights fees and marketing costs.
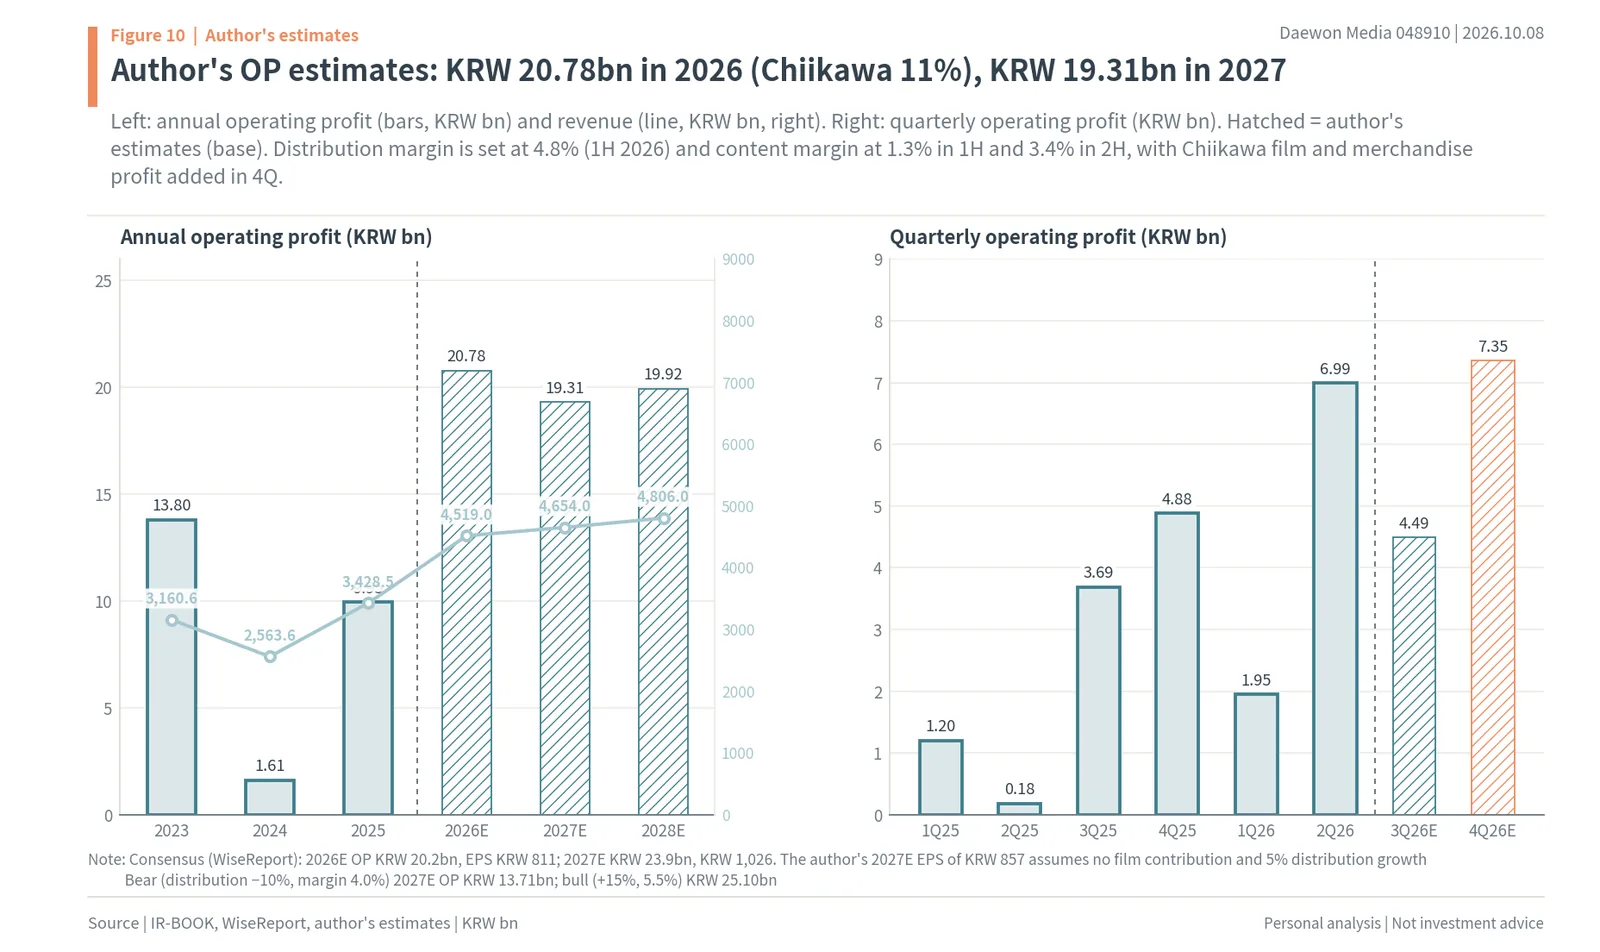
49. At the same ratio, the Chiikawa film’s operating profit is KRW 1.70bn, and KRW 9.6 of every KRW 100 in box office stays with Daewon.
50. In Q1 2023, when The First Slam Dunk was in theaters, Daewon C.I. manga sales pushed publishing revenue KRW 8.56bn above the average of other quarters.
51. Dividing this by The First Slam Dunk’s 4.92 million admissions means KRW 1,740 more was sold per viewer, and this ratio was used for the goods calculation.
52. The reference films left two marks: KRW 9.6 of operating profit per KRW 100 of box office, and KRW 1,740 of attached revenue per viewer.
5. Chiikawa Merchandise: KRW 2.94bn Revenue, KRW 590mn Operating Profit
53. Daewon Media handles licensing for the Meonjakgwi brand in Korea, and there is an official store, Chiikawa Shop Yongsan, in Yongsan, Seoul (opened February 27, 2026).
54. A pop-up store in Yongsan in late 2024 drew about 30,000 visitors in ten days (Daewon Media’s official account).
55. On October 7, in the film’s opening week, 1,253 people were waiting to enter the store, with an expected wait of more than 11 hours (BizHankook).
56. The industry puts daily visitors at 1,400–1,500, and resale listings reached 39,593, with some items reselling at three times their price (Segye Ilbo).
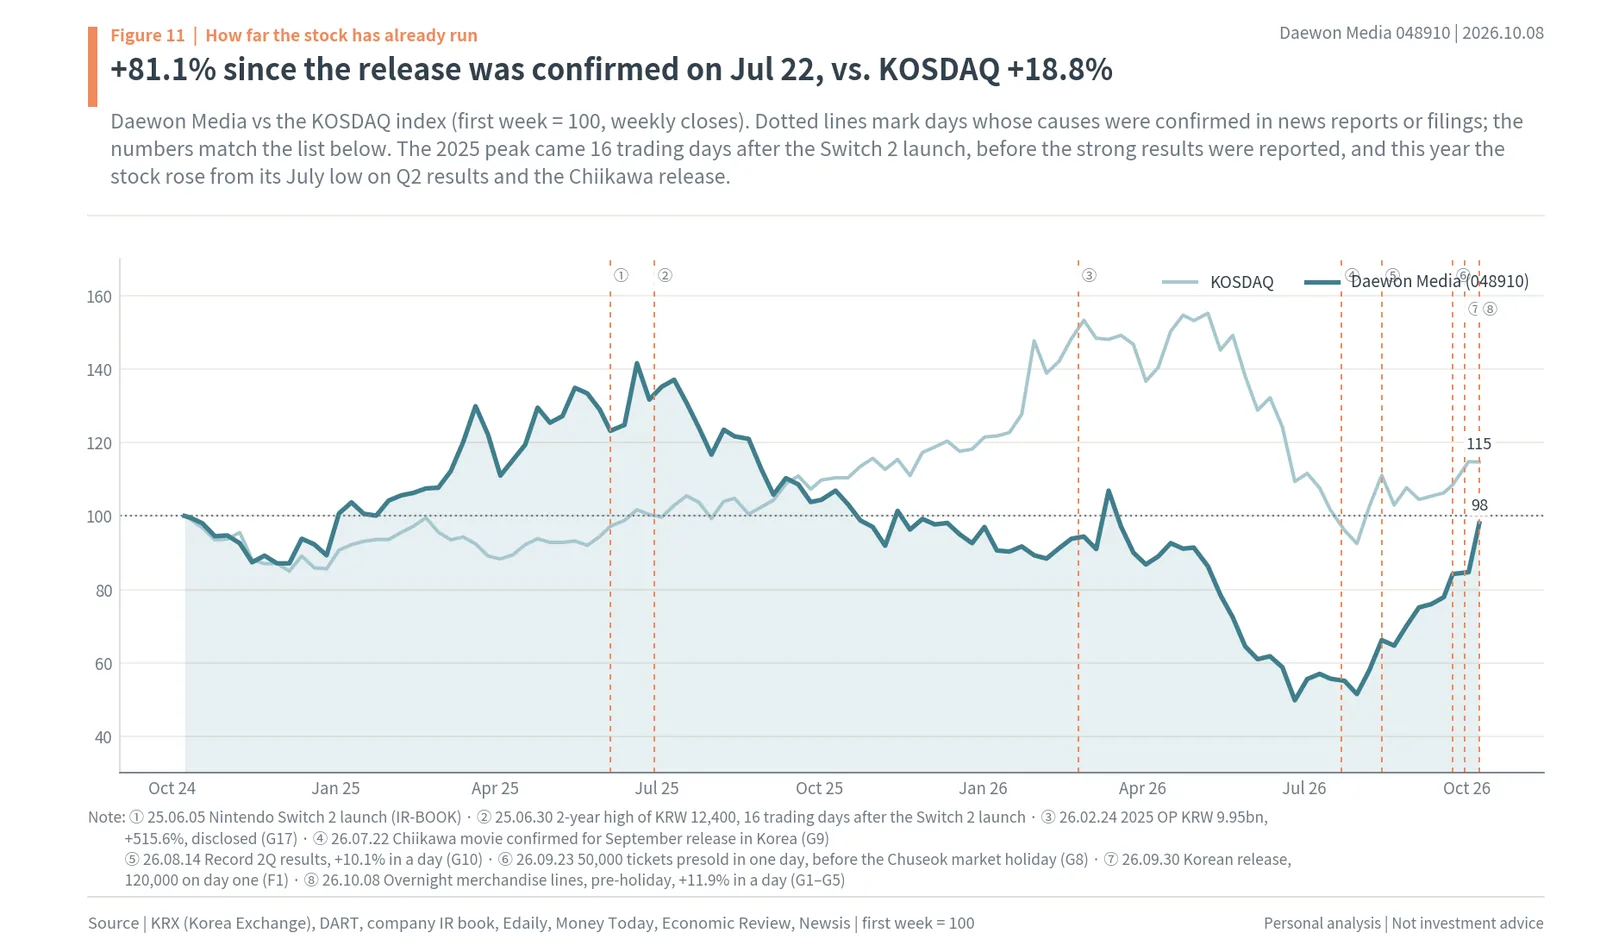
57. The CGV popcorn bucket (KRW 29,000) drew proxy-purchase premiums at 25 theaters, and the official online store’s server went down on the day a SPAO collaboration launched.
58. Additional goods revenue is KRW 2.94bn in the base case at KRW 1,740 per viewer (the Slam Dunk ratio), half that in the bear case and double in the bull case.
59. Because the stores and staff are already in place, assuming the 2025 gross margin of 19.9% is kept on the extra revenue gives operating profit of KRW 590mn.
60. If 1,450 people a day visit the store for three months, that is 133,400 visits, and an extra purchase of about KRW 22,000 per visit gets to the base case.
61. The base case for goods is KRW 2.94bn in revenue and KRW 590mn in operating profit, booked in Q4 along with the film profit.
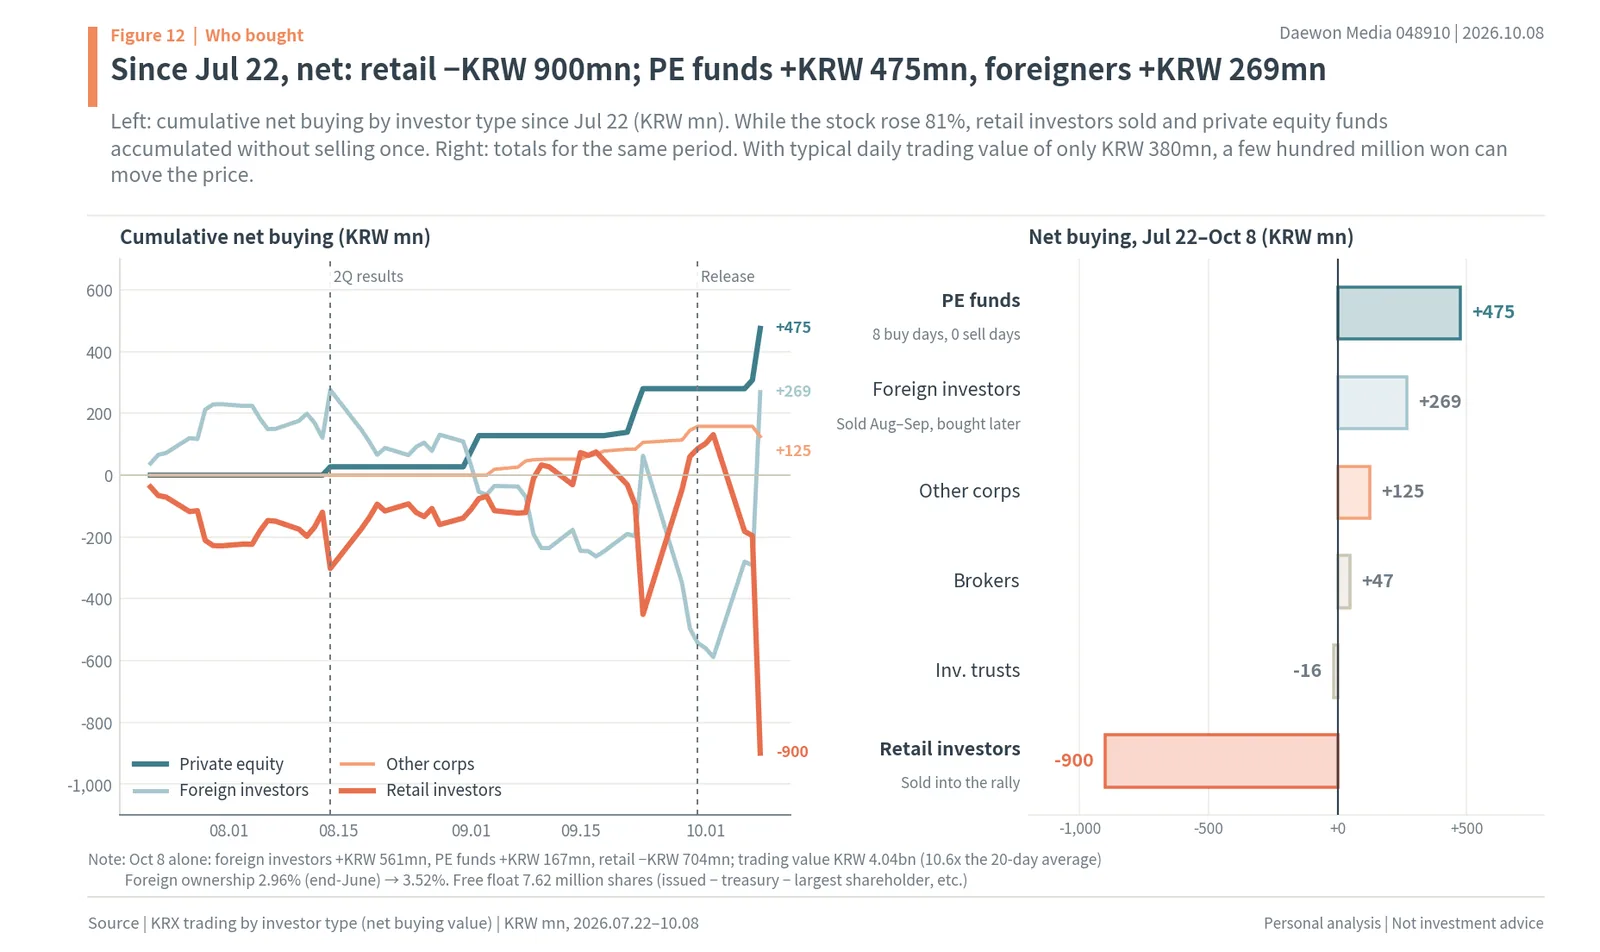
6. Chiikawa Is Worth KRW 139 a Share; the Stock Rose KRW 3,695
62. Adding KRW 1.70bn from the film and KRW 590mn from goods, Chiikawa operating profit is KRW 2.29bn in the base case, KRW 1.08bn in the bear case and KRW 4.92bn in the bull case.
63. After 25% corporate tax, the base case is KRW 1.72bn, and dividing by 12.33 million shares gives KRW 139 a share.
64. The bear case is KRW 66 a share and the bull case KRW 299, and the base value is 1.7% of today’s share price.
65. Yet the share price rose KRW 880 on October 8 alone, and KRW 3,695 since July 22, the day the Korean release was confirmed.
66. Over the same period, market capitalization rose KRW 46.5bn, 27 times Chiikawa’s after-tax profit.
67. The share price bought the expectation ahead of the film’s profit, and the actual profit to back that expectation has to come from Nintendo and hobby distribution.
7. Daewon Media Earnings Forecast: KRW 20.78bn Operating Profit in 2026
68. No brokerage has published a target price in the last three months, and the WISEreport consensus is operating profit of KRW 20.2bn in 2026 and KRW 23.9bn in 2027.
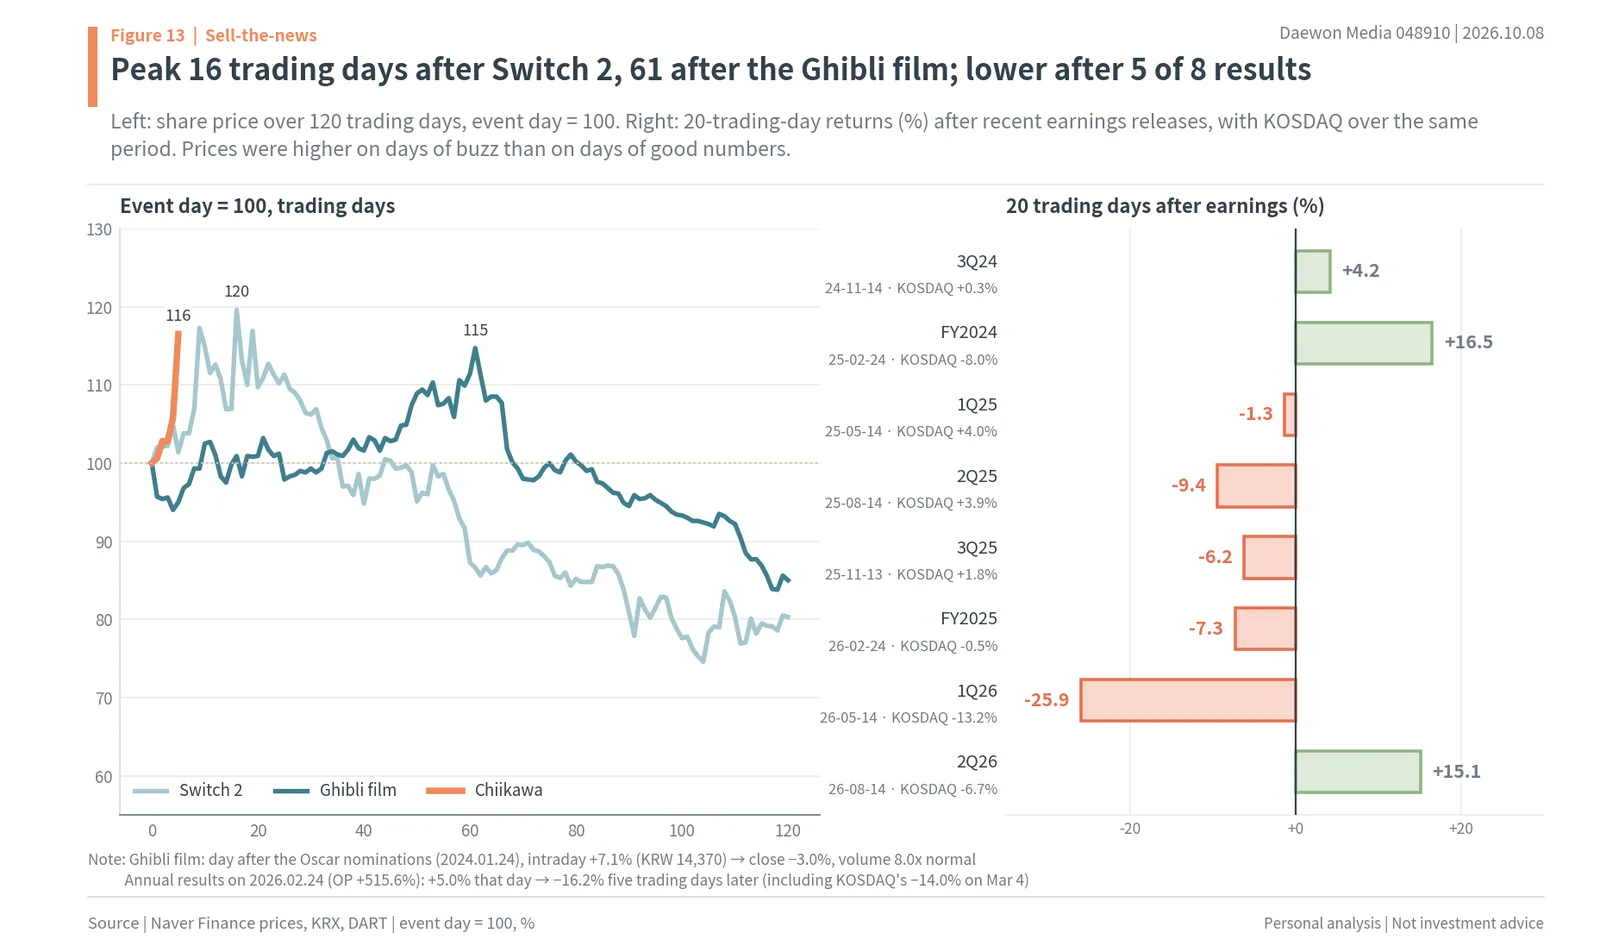
69. The author built a separate estimate from segment revenue: for Q3 and Q4, Nintendo is flat year on year, Shop & Distribution grows 50%, cards grow 20%, and content is flat.
70. Margins are set at 4.8% for distribution (actual first half) and, for content, 1.3% in the first half and 3.4% in the second half (backed out from the second half of 2025).
71. That gives Q3 revenue of KRW 102.87bn and operating profit of KRW 4.49bn, and Q4 operating profit of KRW 7.35bn including KRW 2.29bn from Chiikawa.
72. 2026 operating profit comes to KRW 20.78bn, more than double a year earlier and above the previous record set in 2022 (KRW 14.3bn).
73. For 2027, with the film gone and distribution growing 5%, operating profit is KRW 19.31bn and EPS KRW 857.
74. It is lower than the 2027 consensus of KRW 23.9bn because the Switch 2 enters its third year, so distribution growth was set low at 5%.
75. The Chiikawa film and goods were counted as one-time profit in Q4 and left out of 2027.
76. The bear case (distribution −10%, 4.0% margin) gives 2027 operating profit of KRW 13.71bn, and the bull case (+15%, 5.5%) KRW 25.10bn.
77. The author estimates operating profit of KRW 20.78bn in 2026 (11% from Chiikawa) and KRW 19.31bn in 2027, so once Chiikawa drops out, the distribution margin sets the base.
8. Daewon Media Share Price: +81.1% Since July 22
78. Daewon Media fell from KRW 12,400 on June 30, 2025 (two-year high) to KRW 4,165 on July 29, 2026 (two-year low).
79. From KRW 4,555 on July 22, the day the Korean release was confirmed, the stock rose 81.1% to KRW 8,250 on October 8, while the KOSDAQ rose 18.8% over the same period.
80. Along the way it rose 10.1% on August 14 (record Q2 results), 6.5% on September 23 (advance bookings opened) and 11.9% on October 8 (the goods frenzy).
81. Trading value on October 8 was KRW 4.04bn, 10.6 times the 20-day average (KRW 380mn), and a three-day holiday started the next day.
82. Up 81.1% since the release was confirmed on July 22, against 18.8% for the KOSDAQ, the stock has run ahead of earnings.
9. Who Bought Daewon Media: Retail Sold, Private Equity Funds Bought
83. From July 22 to October 8, retail investors were net sellers of KRW 900mn (KRX trading by investor type).
84. Over the same period, private equity funds were net buyers of KRW 475mn, foreign investors KRW 269mn and other corporations KRW 125mn.
85. Private equity funds first bought on August 14, the results day, bought on eight days in all, and did not sell on a single day.
86. Foreign investors sold into the post-results rally in August and September and bought again after the release, raising their stake from 2.96% at the end of June to 3.52%.
87. On October 8 as well, foreign investors bought KRW 561mn and private equity funds KRW 167mn, while retail investors sold KRW 704mn.
88. Retail net selling that day was 17.4% of trading value, and private equity funds’ purchase that day was their largest single-day buy of the period.
89. With 7.62 million shares in free float and usual daily trading value of KRW 380mn, net buying of a few hundred million won moves the price a lot.
90. The author sees the private equity buying as money meant to be held through Q4 results, because those funds did not sell on any day during the rise.
91. There is no overheating from retail investors piling in yet, and the peak signal is a day when retail investors turn to net buying and private equity funds post their first net sale.
10. Sell-the-News Risk: Switch 2 and The Boy and the Heron Peaked on the Hype
92. On June 5, 2025, the day the Switch 2 launched, Daewon Media was at KRW 10,370, and it peaked at KRW 12,400 on June 30, 16 trading days later.
93. After that it fell 18.9% over 20 trading days and 28.4% over 60 trading days.
94. By August 14, when Q2 results first including Switch 2 sales came out, it was already at KRW 10,250.
95. On October 25, 2023, the day The Boy and the Heron opened, the stock was at KRW 11,700, and it peaked at KRW 13,420 on January 23, 2024, 61 trading days later.
96. That night the Academy Award nominations for Best Animated Feature were announced in the US, and the next day the stock rose as high as KRW 14,370 (+7.1%) intraday before closing at KRW 13,020 (−3.0%).
97. Volume that day was 690,000 shares, 8.0 times normal, and the announcement became the day to sell.
98. Over the next 60 trading days the stock fell 25.7%, and on March 18, when the annual report including the film’s profit came out, it was at KRW 11,060.
99. After 5 of the last 8 earnings releases, the stock was lower 20 trading days later, with a median of −3.8%.
100. On February 24, 2026, when it disclosed a 515.6% rise in operating profit, the stock rose 5.0% but was 16.2% lower five trading days later.
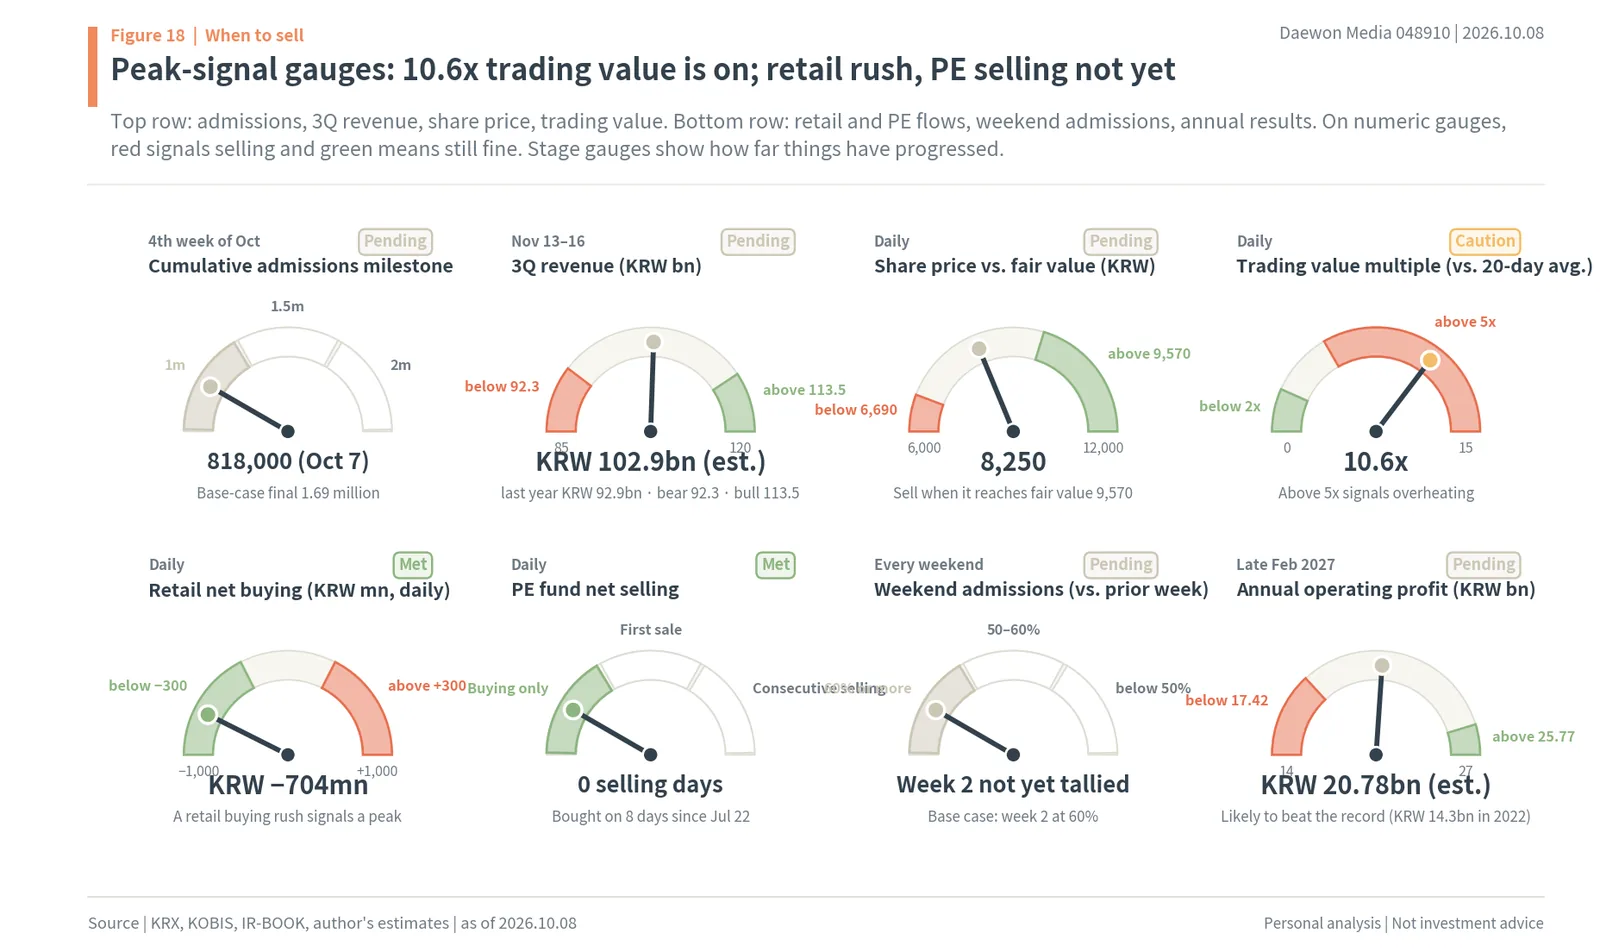
101. Earlier, in 2021, with its own animated series Armored Saurus, the stock rose 28.8% over 10 trading days ahead of the broadcast and then fell 28.9% in a single day on October 12 (Financial News).
102. All three times, the stock rose while the buzz grew, and selling poured in on the day the buzz became fact.
103. The Switch 2 peak came after 16 trading days and the Ghibli film peak after 61, and the stock fell 20 days after 5 of 8 earnings releases, so this company’s sell-the-news moment comes at the peak of the buzz, not with the numbers.
11. Daewon Media Fair Value: KRW 9,570 (Author’s Estimate)
104. Daewon Media’s year-end PER was 47.1x in 2021, 24.4x in 2023 and 18.1x in 2025, high because profits were small in those years.
105. Today it trades at 11.0x trailing four-quarter EPS of KRW 752, 8.0x consensus 2027 EPS of KRW 1,026, and 0.96x PBR.
106. Because most of the profit comes from distribution, the PER is set at 8x in the bear case, 11x in the base case and 14x in the bull case.
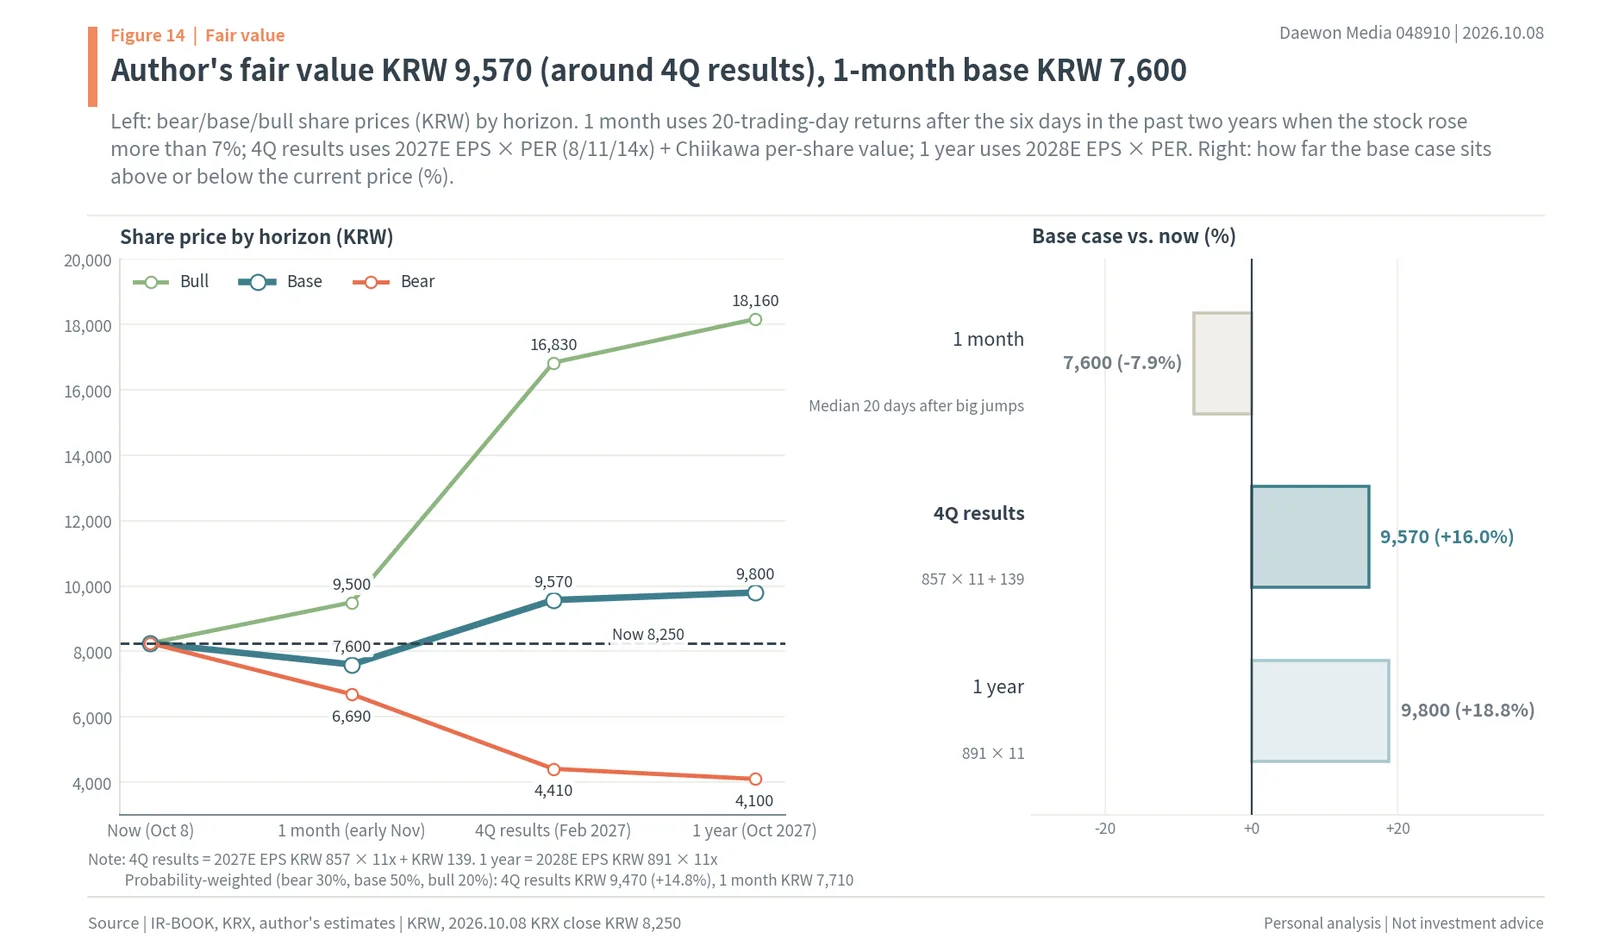
107. Fair value around Q4 results is 2027 EPS of KRW 857 × 11 + KRW 139 for Chiikawa = KRW 9,570, 16.0% above today’s price.
108. The bear case is KRW 4,410 and the bull case KRW 16,830, and weighting bear 30%, base 50% and bull 20% gives KRW 9,470.
109. One year out (October 2027), it is 2028 EPS of KRW 891 × 11 = KRW 9,800.
110. For one month, the author uses the 20 trading days after the six days in the past two years when the stock rose more than 7% (down in 4 of 6, median −7.9%), for a base case of KRW 7,600.
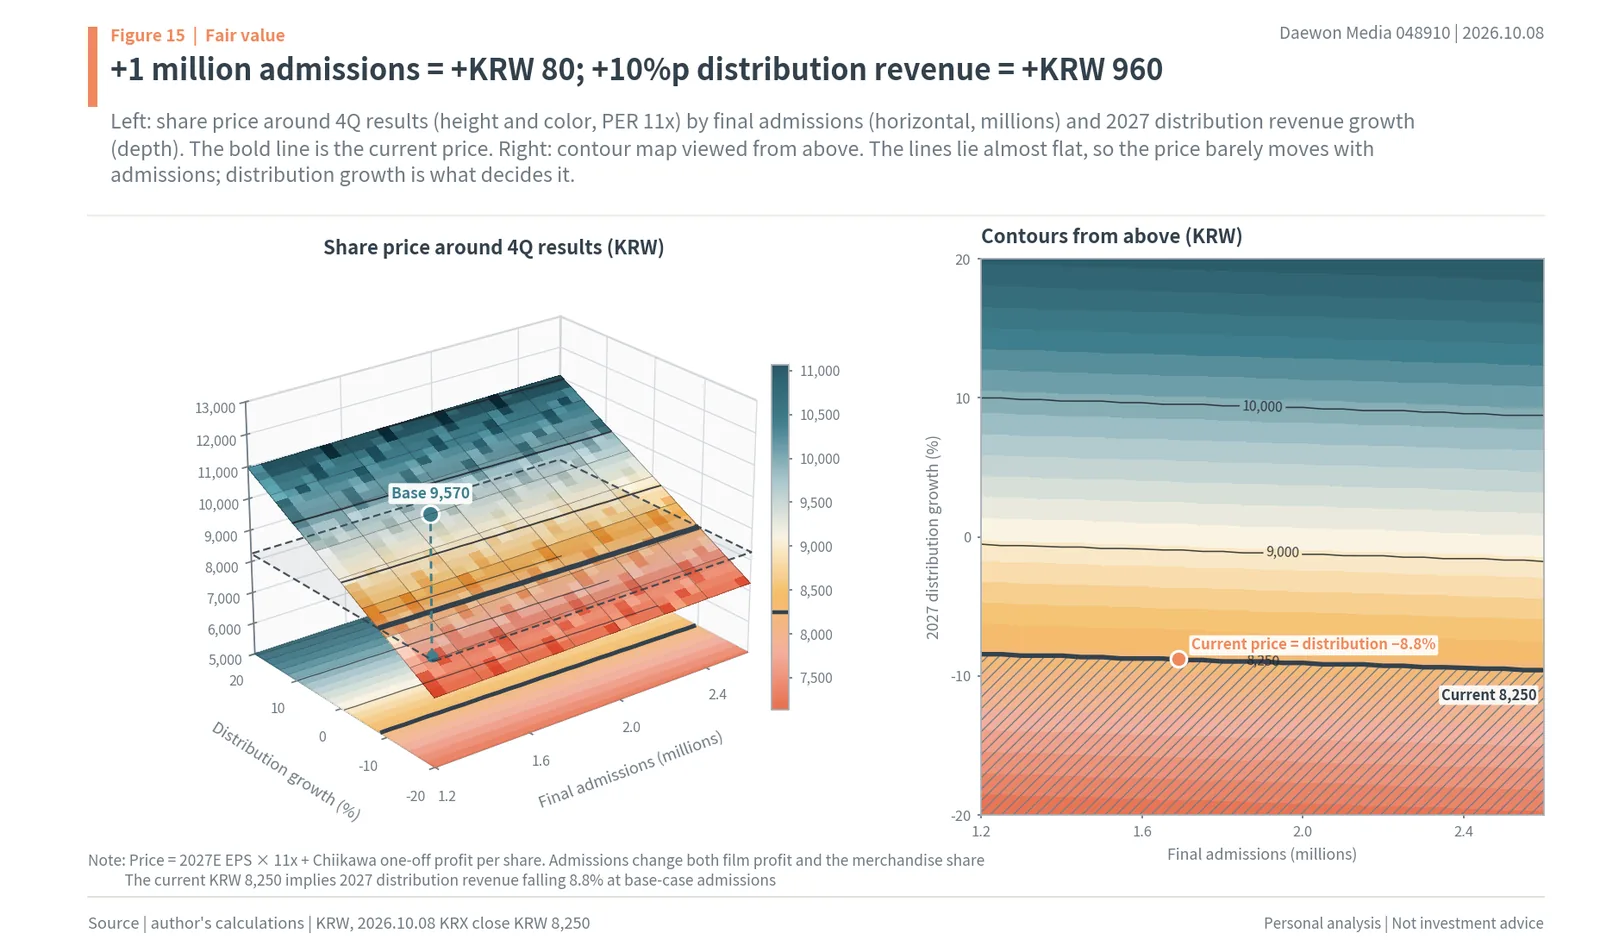
111. As for what moves the value more, 1 million more admissions changes it by KRW 80, while 10 percentage points more growth in 2027 distribution revenue changes it by KRW 960.
112. The contour lines lie almost flat, so distribution growth rather than admissions decides the value, and today’s price of KRW 8,250 matches base-case admissions with 2027 distribution revenue falling 8.8%.
113. 1 million more admissions = +KRW 80 and 10 percentage points more distribution revenue = +KRW 960, so Nintendo and hobby goods are what move fair value.
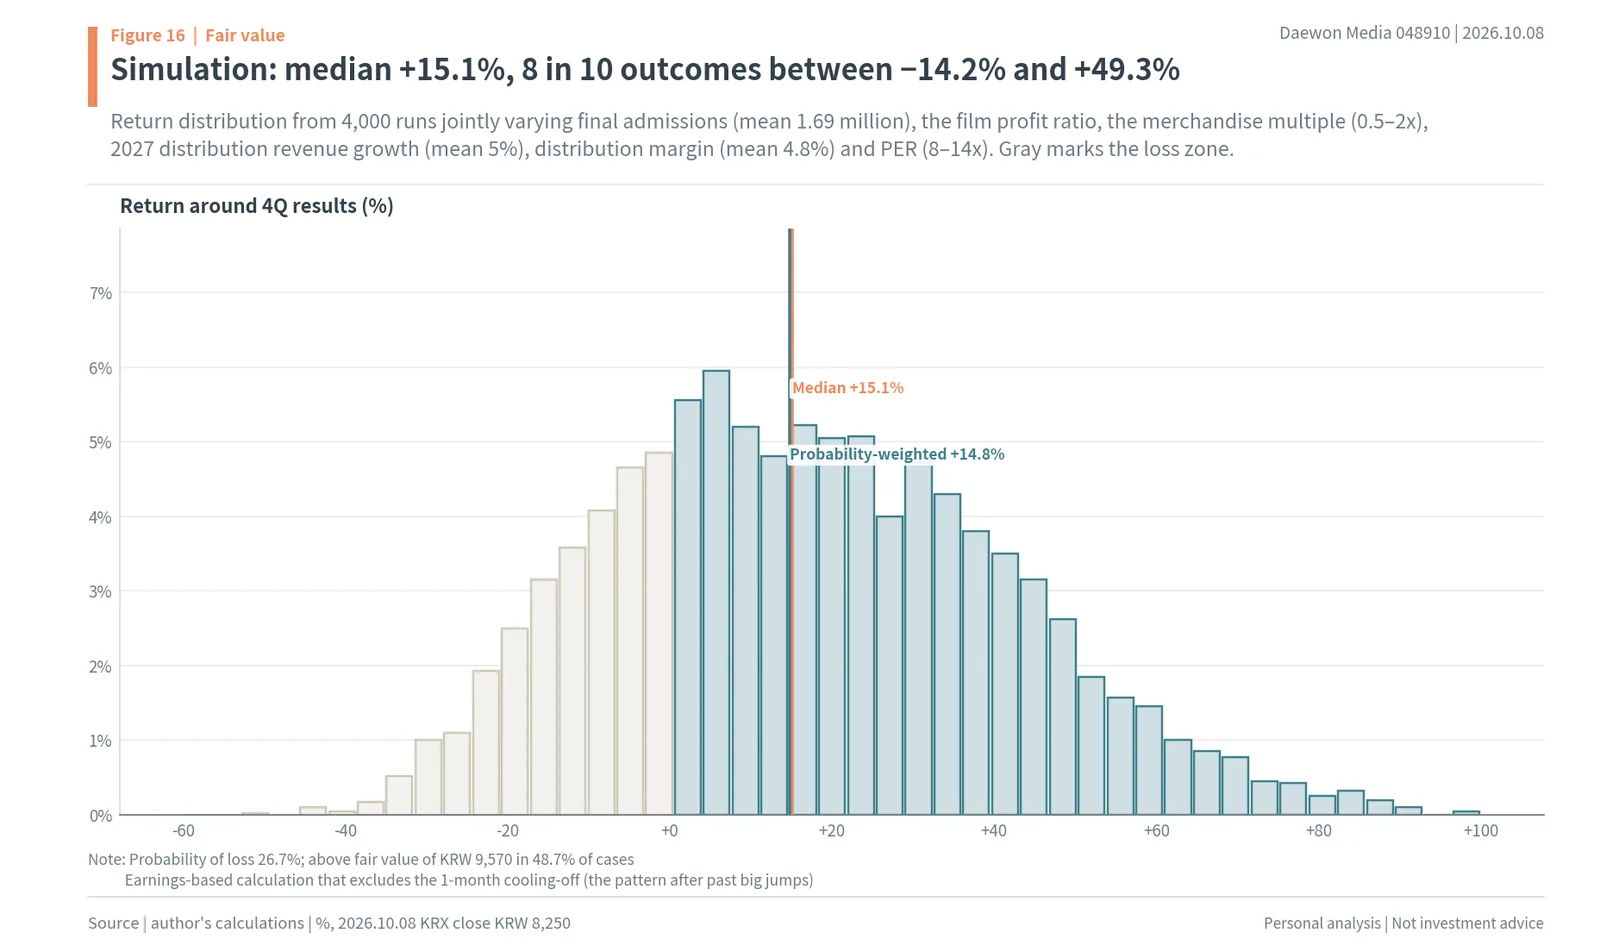
114. Across 4,000 runs that vary admissions, the film profit ratio, the goods multiple, distribution growth, distribution margin and PER together, the median return is +15.1%.
115. Eight in ten runs fall between −14.2% and +49.3%, and the probability of a loss is 26.7%.
116. On earnings there is still room to rise, but over one month the base case is a cooling after a big rally.
12. When to Sell Daewon Media: Selling Calendar and Peak Signals
117. For an investor who sells when good results become the talking point and moves on to the next stock, the starting point is that at this company the peak of the talk has come before the numbers.
118. The first talking point is admissions milestones: in the base case, 1 million comes over the Hangeul Day holiday and 1.5 million in the fourth week of October.
119. The second is Q3 results, which came out on November 13–14 in each of the past three years, with a legal deadline of November 16.
120. The author’s base-case Q3 revenue of KRW 102.87bn is 10.7% above Q3 last year, and operating profit of KRW 4.49bn is 21.7% higher.
121. The third is full-year results in late February 2027, and operating profit of KRW 20.78bn would be a record, making it the biggest numbers story.
122. But that comes after the film’s buzz has faded, so as with the Ghibli film, the stock is likely to have already come down by the day the numbers arrive.
123. So the author sees the first selling window as late October to mid-November, when 1.5 million admissions and Q3 results overlap.

124. If a signal comes before that, that day is the window, and the first signal is the day the stock reaches the KRW 9,570 fair value.
125. The second is a day when retail investors turn to net buying and private equity funds make their first net sale; with retail investors selling and zero selling days from private equity, it is still off.
126. The third is a week when weekend admissions fall below half of the previous weekend’s, a sign that the film story is fading.
127. Trading value at 10.6 times normal is already on, so if one more of the remaining signals turns on, the author reads it as near the peak.
128. On the peak-signal gauges, 10.6x trading value is on while retail piling in and private equity selling are not yet, and money moving to the next stock can be placed the same way, in expectations not yet priced in.
13. Summary
129. The Chiikawa movie reaches a base case of 1.69 million admissions in Korea and leaves Daewon operating profit of KRW 1.7bn from the film and KRW 600mn from goods, worth KRW 139 a share.
130. Nintendo and hobby distribution profit sets most of the KRW 9,570 fair value, and today’s price assumes 2027 distribution revenue falls 8.8%.
131. With the Switch 2 and the Ghibli film, this stock peaked on the day of peak buzz, and after 5 of 8 earnings releases it was lower 20 trading days later.
Maochaedung’s take
Chiikawa put people in line, but Nintendo makes Daewon Media’s profit. The KRW 2.3bn of operating profit left by the base case of 1.69 million admissions is worth KRW 139 a share, and the KRW 9,570 fair value is the value of the distribution business at 11 times 2027 EPS of KRW 857. With the Switch 2 and the Ghibli film, the share price peaked on the day of peak buzz and came down before the numbers came out, so for an investor who sells on the earnings story, the first window is late October to mid-November, when 1.5 million admissions and Q3 results overlap, or the day the stock reaches KRW 9,570.
Daewon Media and Chiikawa Stock FAQ
Q. Is Daewon Media the distributor of the Chiikawa movie in Korea?
According to KOBIS, Daewon Media is the importer and CJ ENM is the distributor. After VAT and the film levy, theaters and the distributor split ticket revenue in half, and after CJ ENM’s 10% fee, 39.7% of the box office reaches Daewon Media.
Q. How many people will see the Chiikawa movie in Korea?
It had 818,000 admissions after 8 days. The author’s base case is 1.69 million final admissions (bear 1.47 million, bull 2.21 million), 14.4% of Japan’s 11.78 million. The Boy and the Heron, which Daewon also imported, drew 2.02 million in Korea.
Q. How much does Chiikawa add to Daewon Media’s profit?
In the author’s base case, the film adds KRW 1.7bn and Chiikawa merchandise KRW 590mn of operating profit, KRW 2.29bn in total, or KRW 139 a share after tax. That is 1.7% of the KRW 8,250 share price.
Q. What is Daewon Media’s fair value?
The author’s fair value at Q4 results is KRW 9,570 (2027E EPS of KRW 857 × 11 + KRW 139 from Chiikawa), 16.0% above today. The one-month base case is KRW 7,600.
Q. Who bought Daewon Media’s rally?
From July 22 to October 8, retail investors net-sold KRW 900mn, while private equity funds net-bought KRW 475mn and foreign investors KRW 269mn. The funds bought on 8 days and sold on none.
Q. Will there be a sell-the-news drop, and when should I sell?
Daewon Media peaked 16 trading days after the 2025 Switch 2 launch and 61 trading days after The Boy and the Heron’s 2023 release, before the good results were reported. The author sees late October to mid-November, when 1.5 million admissions and Q3 results coincide, as the first selling window.
Sources
- Daewon Media, 2026 half-year IR-BOOK (link), 2026.09.11
- Daewon Media, 2025 full-year IR-BOOK (link), 2026.03.11
- Financial Supervisory Service DART, Daewon Media half-year report (link), 2026.08.14
- Financial Supervisory Service DART, Change of 30% or more in revenue or profit structure (link), 2026.02.24
- Korean Film Council KOBIS, Daily box office, film information and 2023 annual box office (link), accessed 2026.10.08
- eiga.com, Chiikawa movie box office (link), 2026.09.21
- Real Sound, Chiikawa movie box office after 75 days (link), 2026.10.07
- Newspim, Chiikawa movie opens in Korea (link), 2026.09.30
- Newsis, Overnight lines at the Chiikawa Shop (link), 2026.10.08
- Newsis, The Chiikawa craze and marketing (link), 2026.10.08
- Segye Ilbo, Chiikawa Shop visitors and resale trading (link), 2026.10.08
- BizHankook, The Chiikawa craze in Korea (link), 2026.10.08
- Cine21, How box office revenue is split (link), 2026.07.30
- KOBIZ, Film import guide (link)
- MANTANWEB, Box office of Suzume, The First Slam Dunk and The Boy and the Heron (link), 2023.05.29
- iMBC, Korean admissions for The Boy and the Heron (link), 2023
- Anime News Network, Academy Award nominations announced (link), 2024.01.23
- Money Today, Daewon Media’s record Q2 results (link), 2026.08.14
- Edaily, Chiikawa’s Korean release confirmed (link), 2026.07.22
- Economic Review, Chiikawa advance bookings surge (link), 2026.09.23
- Bloter, Daewon Media distribution segment H1 results (link), 2026.08.17
- Korea IR Service Corporate Research Center, Daewon Media (link), 2025.11.12
- Edaily, Demon Slayer: Infinity Castle admissions and box office (link), 2025.08.27
- Green Economy Newspaper, Chiikawa collaboration and server outage (link), 2026.10.08
- Etoday, CGV Chiikawa popcorn bucket (link), 2026.09
- Daewon Media official X, Chiikawa (Meonjakgwi) Festa (link), 2024.12
- Economic Review, Chiikawa advance booking ranking (link), 2026.10.08
- Financial News, Armored Saurus catalyst fades (link), 2021.10.12
- Korea Exchange (KRX), Daewon Media share price, KOSDAQ index and trading by investor type, 2026.10.08 / Naver Finance prices (reference share prices, 2020–2024)
- WISEreport, Daewon Media consensus, accessed 2026.10.08
Disclaimer
This post records the author’s personal analysis and views based on publicly available information and does not recommend choosing any particular product or company. It does not recommend buying or selling any financial investment product and is not a service provided as investment advisory or quasi-investment advisory business.
Figures in this post are values published as of the time of writing. Final admissions, the film and goods operating profit, and the 2026–2028 earnings and EPS are estimates from a model the author built, not company guidance or broker consensus. The film profit ratio is the author’s assumption calibrated to the difference in Q4 results at the time of The Boy and the Heron in 2023, and the goods share is calibrated to the difference in publishing revenue at the time of The First Slam Dunk in 2023; the company does not disclose revenue by film or by character. Accuracy and completeness are not guaranteed.
The share price ranges by deadline, the scenarios and the selling times are estimates based on the assumptions stated in the text and on past share price cases, and results will differ if those assumptions do not hold. Items marked ‘author’s calculation’ or ‘author’s estimate’ are the author’s calculations and assumptions, not confirmed facts.
The share price ranges and selling windows in this post are the author’s personal views and calculations; they do not recommend trading at any particular time or promise any return. Daewon Media is listed in Korea and trades in Korean won, so for overseas investors, gains and losses in your home currency change with exchange rates.
Author’s interest: not disclosed
Responsibility for decisions and their outcomes lies with the reader.
As of: October 8, 2026